
What Fort Wayne Area Homeowners Should Do After Hail
Discuss your property →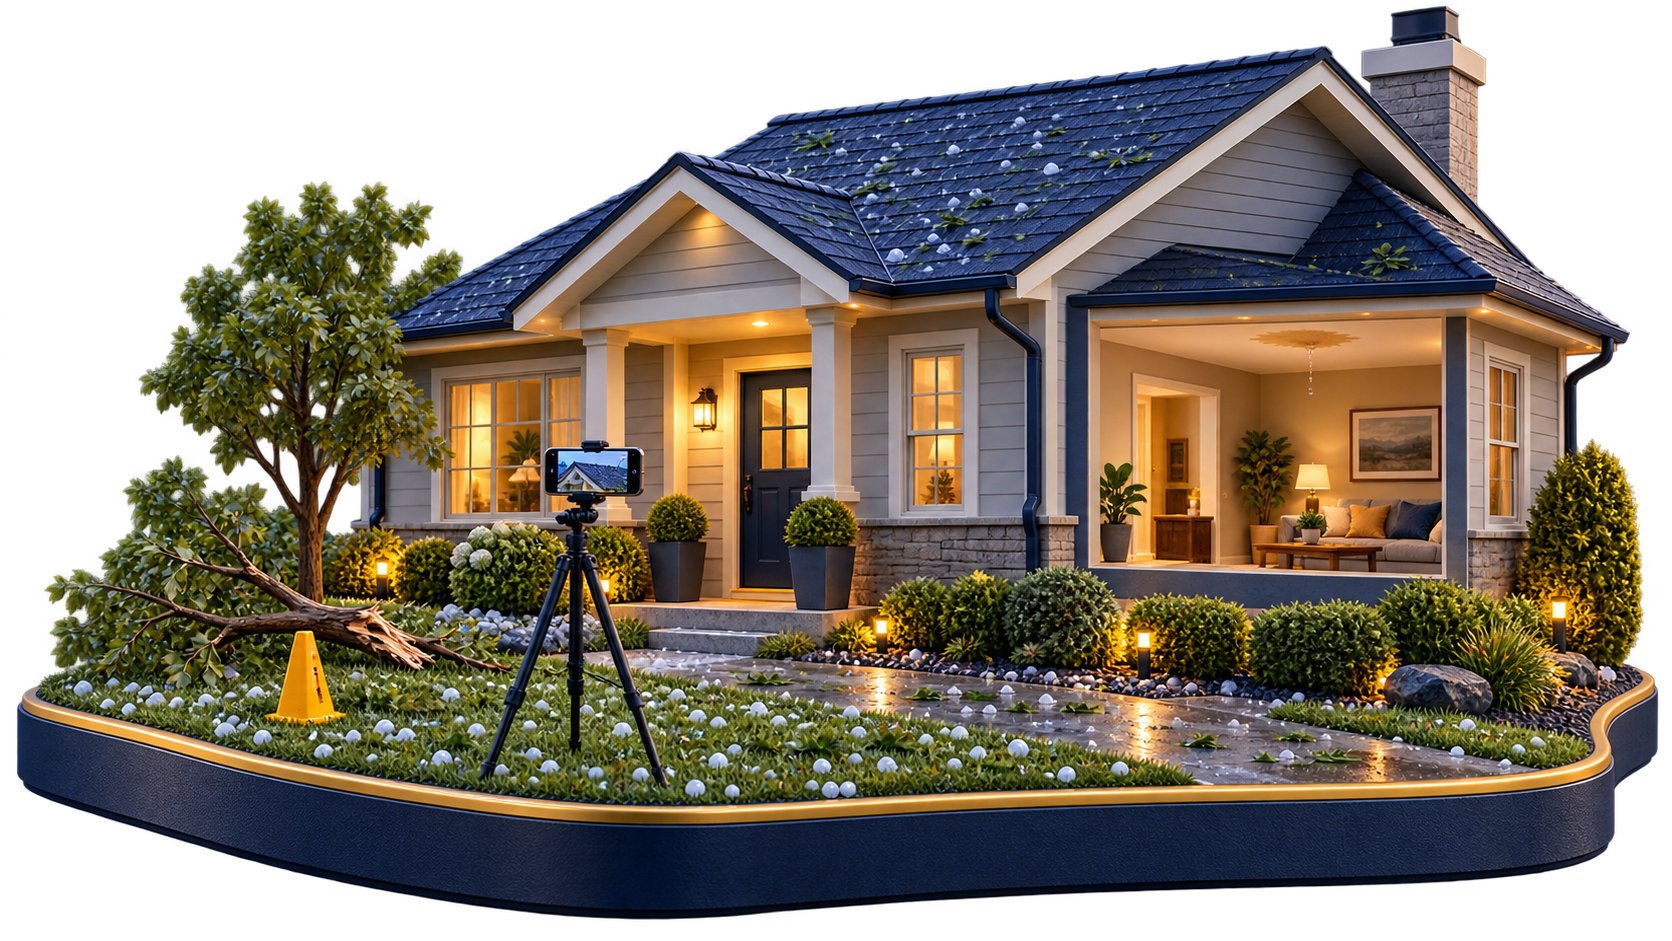
- 01Immediate safety
- 02Document conditions
- 03Written construction review
What should you do after hail near Fort Wayne?
After hail or severe wind near Fort Wayne, wait until the threat has passed and check only from a safe location. Look from the ground for displaced roofing, damaged vents or gutters, debris impact, and interior water signs. Photograph visible conditions, take reasonable steps to limit additional damage when it is safe, review the policy, and contact the insurer if a covered loss may have occurred. A roofing contractor can document construction conditions and prepare a proposed scope; the insurer decides coverage and claim payment.
Do not climb onto a wet, steep, icy, or possibly damaged roof. Stay clear of downed lines, unstable trees, loose materials, and active water near electrical equipment. If water is entering near electrical fixtures or creates an immediate safety concern, use the appropriate emergency or utility contact before arranging a routine roof review.
Safe response sequence
| Check | What to record or do | Decision it supports |
|---|---|---|
| Immediate safety | Wait for the threat to pass; stay clear of downed lines, unstable trees, loose materials, and active water near electrical equipment | Whether emergency or utility help is needed before a routine roof review |
| Visible exterior changes | Photograph displaced roofing, damaged vents or gutters, debris impact, and other changes from a safe ground-level location | Which areas need closer professional review |
| Interior water signs | Record dripping, staining, damp materials, odors, and the rooms or fixtures involved | Whether temporary protection or urgent specialist help may be needed |
| Temporary protection | Use only reasonable measures that can be performed safely; keep receipts and photographs | Documentation of steps taken to limit additional damage |
| Policy and claim records | Review the policy, keep correspondence, and ask the insurer about required notice and inspection steps | Which insurance records and deadlines apply to the property |
| Written construction review | Request findings tied to specific areas, access limits, photographs, and a proposed scope when enough information exists | Whether monitoring, localized repair, broader evaluation, or specialist review should follow |
Which visible conditions justify a professional roof assessment?
One visible condition does not prove the full extent or cause of a roof problem. A professional assessment may be appropriate when you observe:
- missing, lifted, torn, cracked, or displaced roof covering;
- fresh impact marks on metal vents, gutters, downspouts, flashing, or other exterior components;
- debris strikes or fallen branches;
- water staining, dripping, damp insulation, or a new interior odor;
- displaced ridge, edge, or penetration components;
- a new change that appeared after the storm, even when no active leak is visible.
Some roof conditions are visible only from appropriate access points, and some are concealed beneath the roof covering. A ground-level photograph cannot establish decking condition, hidden moisture, code compliance, material compatibility, or insurance coverage.
What should a written roof-condition review document?
A useful record should separate observed conditions from conclusions that require more evidence. Subject to access and safety limits, a written review may include:
- the property and areas observed;
- the date, access method, weather limitations, and inaccessible areas;
- photographs tied to specific roof or exterior locations;
- the roof covering and visible accessory components;
- visible conditions that may need repair, monitoring, specialist review, or broader evaluation;
- any limitation that prevents a reliable conclusion;
- a proposed construction scope when enough information exists.
The report should not promise coverage, claim value, approval, replacement, or a particular insurer response. If structural, electrical, solar, chimney, hazardous-material, or concealed-condition questions arise, the appropriate qualified professional may need to review them separately.
How is repair versus replacement evaluated after a storm?
The decision is not based on hail size, roof age, or one photograph alone. The review should consider the cause and extent of the condition, whether matching material is available, whether a durable repair can be completed under current manufacturer instructions, the condition of decking and flashing, the roof geometry, applicable code and permit requirements, and whether repeated repairs would leave unresolved system problems.
A limited repair may be considered when the affected area is identifiable, compatible material and components are available, surrounding roofing can support the work, and the repair can follow current installation requirements. Broader replacement evaluation may be appropriate when conditions are widespread, the roof system cannot be reliably integrated, concealed deterioration is discovered, or the required scope extends beyond a localized repair.
These are construction considerations, not coverage decisions. The signed scope, policy, insurer inspection, and any required specialist reports remain separate records.
Can hail damage a roof without causing an immediate leak?
Yes, a roof can show storm-related changes without an immediate interior leak, and an interior leak can have causes other than hail. That is why the useful question is not simply whether water is visible today. The assessment should document what changed, where it appears, whether the roof remains serviceable, and what additional review is needed.
Do not delay emergency water control when active entry threatens the building or contents. At the same time, avoid permanent repairs that erase useful documentation before the insurer or other responsible party has had a reasonable opportunity to review the condition.
Can a roofer decide whether insurance covers the work?
No. A roofer can describe visible construction conditions, prepare photographs and measurements, recommend a construction scope, and explain repairability or installation requirements. The insurer interprets the policy and decides coverage and claim payment. Legal or policy disputes belong with the appropriately licensed or qualified adviser, not with an unsupported marketing promise.
Homeowners should keep copies of photographs, estimates, reports, invoices, policy communications, and signed agreements. Before authorizing work, confirm the contractor identity, written scope, price and payment terms, change-order process, permit responsibility, warranty documents, and who will communicate with the insurer.
Are Class 3 or Class 4 shingles hail-proof?
No. Class 3 and Class 4 describe impact-test performance under a defined standard; they do not mean a product cannot be damaged. The test result is one input alongside the complete roof system, local availability, wind and installation requirements, repairability, warranty terms, budget, and the insurer’s treatment of the exact product.
Pinnacle must confirm the exact product and complete accessory system available for the installation ZIP code before presenting an option as available. Homeowners should also ask the insurer whether the product and installation documentation affect the policy or any available credit. No discount or coverage result should be assumed.
What should Fort Wayne-region homeowners confirm before signing?
Use the written proposal and supporting records to confirm:
- the exact property and work area;
- the observed condition and the proposed construction response;
- materials, colors, accessories, ventilation, flashing, and underlayment;
- removal, disposal, protection, and cleanup responsibilities;
- permit, inspection, and code responsibilities;
- price, deposit, progress-payment, and change-order terms;
- start conditions, access limits, weather delays, and cancellation terms;
- manufacturer and installer warranty documents;
- responsibility for solar, electrical, chimney, structural, or other specialist work;
- who owns and receives photographs, reports, and project records.
Do not sign a blank scope or rely on an oral promise that conflicts with the written agreement. Before signing, confirm applicable Indiana contract, licensing, insurance, permitting, and consumer-protection requirements with the responsible authority.
Where is Pinnacle currently considering Fort Wayne-area work?
Pinnacle’s current working direction is generally within approximately 50 miles of downtown Fort Wayne, subject to ZIP code, service capacity, trade requirements, and project confirmation. This is not a claim of statewide Indiana coverage and does not guarantee availability at a particular address.
When requesting a review, provide the property ZIP code, the approximate storm date, any active water entry, and what you can safely observe. Pinnacle will confirm whether the address and requested scope are within the current operating area before scheduling.
Frequently asked questions
Should a roof be replaced because it is old and was exposed to hail?
Not automatically. Age can affect repairability, material matching, condition, and remaining serviceability, but the decision should use the actual observed system and the proposed scope.
Should I climb onto the roof to look for hail damage?
No. Use safe ground-level observations and interior checks. Roof access should be limited to people with the appropriate training, equipment, and conditions.
What if water is entering the home?
Protect people first, stay clear of electrical hazards, document the condition when safe, and use reasonable temporary measures that do not create another hazard. Keep receipts and photographs. Emergency control does not determine insurance coverage.
Can photographs prove the roof needs replacement?
Photographs can document visible conditions, but they do not establish concealed conditions, complete repairability, code requirements, or policy coverage by themselves.
Can a roofing contractor negotiate my insurance claim?
A contractor may document construction conditions and provide a scope or estimate. The insurer decides coverage and payment. Any activity reserved to a licensed public adjuster, attorney, or other professional must remain with that qualified party.
Request a documented roof-condition review
Tell Pinnacle your ZIP code, the approximate storm date, whether water is entering the home, and what you observed from a safe location. Pinnacle will confirm Fort Wayne-region availability and the appropriate next step before scheduling.
Sources
- National Weather Service, Indiana severe-weather climatology
- National Weather Service, thunderstorm safety
- Ready.gov, thunderstorms and lightning
- UL Solutions and IBHS, residential roofing-shingle testing overview
- IKO Cambridge product page
- IKO Dynasty product page
- IKO Nordic product page
- Indiana Department of Insurance, insurance claim tips, reviewed October 30, 2026.
- Indiana Attorney General, finding a contractor after the storm, reviewed October 30, 2026.
- Allen County Building Department, 2026 residential permit guide, reviewed October 30, 2026; roofing and siding permits and construction-plan submission are property- and scope-dependent.